a neat EM resolution

Read (and answered) this question on X validation about finding the maximum likelihood estimator of a 2×2 Gaussian covariance matrix when some observations are partly missing. The neat thing is that, in this case, the maximisation step is identical to the maximum likelihood estimation of the 2×2 Gaussian covariance matrix by redefining the empirical covariance matrix into Z and maximising
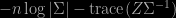
in Σ. Nothing involved but fun to explain, nonetheless. (In my final exam this year, no student even approached the EM questions!)
Leave a Reply