integral theorems for Monte Carlo
 Nhat Ho and Stephen G. Walker have just arXived a paper on the use of (Fourier) integral theorems for Monte Carlo estimators, following the earlier entry of Parzen: namely that for any integrable function,
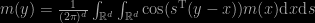
which can be turned into an estimator of a density m based on a sample from m. This identity can be rewritten as
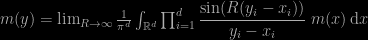
and the paper generalises this identity to all cyclic functions. Even though it establishes that sin is the optimal choice. After reading this neat result, I however remain uncertain on how this could help with Monte Carlo integration.
August 12, 2021 at 12:09 pm
Ho and Walker shows how Fourier integrals lead to natural Monte Carlo estimators in an earlier paper:
Ho, N. and Walker, S.G., 2020. Multivariate smoothing via the Fourier integral theorem and Fourier kernel. arXiv preprint arXiv:2012.14482.