 Among the many interesting arXived papers this Friday, I first read David Aldous’ “Interacting particle systems as stochastic social dynamics“. Being unfamiliar with those systems (despite having experts in offices down the hall in Paris-Dauphine!), I read this typology of potential models (published in Bernoulli) with a keen interest! The paper stemmed from a short course given in 2012 in Warwick and Cornell. I think the links exhibited there with (social) networks should be relevant for statisticians working on networks (!) and dynamic graphical models. Statistics is not mentioned in the paper, except for the (misleading) connection with statistical physics, but there is obviously a huge potential for statistical inference, from parameter estimation to model comparison. (As pointed out by David Aldous, there is usually “no data or evidence linking the model to the asserted real-world phenomena”.) The paper then introduces some basic models like the token, the pandemic and the averaging process, plus the voter model that relates to Kingman’s coalescent. A very nice read opening new vistas for sure (and a source of projects for graduate students most certainly!)
Archive for Bernoulli
interacting particle systems as… facebook
Posted in Books, Statistics, University life with tags Bernoulli, David Aldous, Facebook, Galton-Watson process, interacting particle systems, Kingman's coalescent on October 8, 2013 by xi'anAnother Bernoulli factory
Posted in R, Statistics with tags Bernoulli, MCMC, perfect sampling on February 14, 2011 by xi'an The paper “Exact sampling for intractable probability distributions via a Bernoulli factory” by James Flegal and Radu Herbei got posted on arXiv without me noticing, presumably because it came out just between Larry Brown’s conference in Philadelphia and my skiing vacations! I became aware of it only yesterday and find it quite interesting in that it links the Bernoulli factory method I discussed a while ago and my ultimate perfect sampling paper with Jim Hobert. In this 2004 paper in Annals of Applied Probability, we got a representation of the stationary distribution of a Markov chain as

where
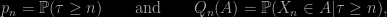
the stopping time τ being the first occurrence of a renewal event in the split chain. While 


