
Archive for integral priors
on(-line) integral priors for model selection
Posted in Books, Statistics, University life with tags Bayes factor, Bayesian model selection, collaboration, ergodicity, improper priors, integral priors, International Statistical Review, ISI, Juan Antonio Cano, Markov chains, MCMC, noninformative priors, open access, paper, reference priors on February 27, 2026 by xi'an
integral priors for model comparison [2.0]
Posted in Books, Statistics, University life with tags arXiv, Bayesian inference, Bayesian model choice, Bayesian statistics, ergodicity, imaginary training sample, integral priors, Juan Antonio Cano, Markov chain, MCMC, Murcia, nested models, noninformative priors, reference priors, Spain, Universidad de Murcia on May 2, 2025 by xi'an
null recurrent = zero utility?
Posted in Books, R, Statistics with tags ergodicity, integral priors, Markov chain, Markov kernel, MCMC, null recurrence, R, simulation on April 28, 2022 by xi'an The stability result that the ratio
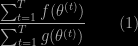
converges holds for a Harris π-null-recurrent Markov chain for all functions f,g in L¹(π) [Meyn & Tweedie, 1993, Theorem 17.3.2] is rather fascinating. However, it is unclear it can be useful in simulation environments, as for the integral priors we have been studying over the years with Juan Antonio Cano and Diego Salmeron Martinez. Above, the result of an experiment where I simulated a Markov chain as a Normal random walk in dimension one, hence a Harris π-null-recurrent Markov chain for the Lebesgue measure λ, and monitored the stabilisation of the ratio (1) when using two densities for f and g, to its expected value (1, shown by a red horizontal line). There is quite a variability in the outcome (repeated 100 times), but the most intriguing is the quick stabilisation of most cumulated averages to values different from 1. Even longer runs display this feature
 which I would blame on the excursions of the random walk far away from the central regions for both f and g, that is on long sequences where zeroes keep being added to numerator and denominators in (1). As far as integral approximation is concerned, this is not very helpful!
Juan Antonio Cano Sanchez (1956-2018)
Posted in Statistics, University life with tags Bayesians, integral priors, Juan Antonio Cano, Murcia, O'Bayes 2015, Objective Bayesian hypothesis testing, Spain, Universidad de Murcia, Valencia conferences on October 12, 2018 by xi'an I have just learned the very sad news that Juan Antonio Cano, from Universidad de Murcia, with whom Diego Salmerón and I wrote two papers on integral priors, has passed away, after a long fight against a kidney disease. Having communicated with him recently, I am quite shocked by him passing away as I was not aware of his poor health. The last time we met was at the O’Bayes 2015 meeting in Valencià, with a long chat in the botanical gardens of the Universitat de Valencià. Juan Antonio was a very kind and unassuming person, open and friendly, with a continued flow of research in Objective Bayes methodology and in particular on integral priors. Hasta luego, Juan Antonio!
Objective Bayesian hypothesis testing
Posted in Books, Statistics, University life with tags academic journals, binomial regression, integral priors, Objective Bayesian hypothesis testing, Statistica Sinica on June 19, 2015 by xi'an Our paper with Diego Salmerón and Juan Cano using integral priors for binomial regression and objective Bayesian hypothesis testing (one of my topics of interest, see yesterday’s talk!) eventually appeared in Statistica Sinica. This is Volume 25, Number 3, of July 2015 and the table of contents shows an impressively diverse range of topics.

