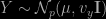Archive for Roman Forum
carcere mamertino [jatp]
Posted in pictures, Travel with tags Capitol, Capitoline Hill, Carcer o Tullianum, Carcere Mamertino, Foro Romano, jatp, Roma, Roman Forum, Rome on July 1, 2024 by xi'an
vacanze romane [jatp]
Posted in Statistics with tags antiquity, history, Italia, jatp, Roma, Roman Empire, Roman Forum, Rome, Santa Maria di Loreto, Trajan column, vacations on May 7, 2019 by xi'an
shiny evening at the stadium [jatp]
Posted in Statistics with tags clouds, Coliseo, fori romani, Italia, Italy, jatp, Roma, Roman Forum, SPQR, sunset on May 5, 2019 by xi'an
buona sera da Roma [jatp]
Posted in Statistics with tags fori romani, forum, Italia, jatp, Roma, Roman Forum, sunset, Vittorio Emanuele II Monument on May 4, 2019 by xi'an
seminar at CREST on predictive estimation
Posted in pictures, Statistics, University life with tags Bayesian predictive, CREST, ENSAE, Kullback, Malakoff, Montpellier, Québec, Roma, Roman Forum on March 6, 2012 by xi'an On Thursday, March 08, Éric Marchand (from Université de Sherbrooke, Québec, where I first heard of MCMC!, and currently visiting Université de Montpellier 2) will give a seminar at CREST. It is scheduled at 2pm in ENSAE (ask the front desk for the room!) and is related to a recent EJS paper with Dominique Fourdrinier, Ali Righi, and Bill Strawderman: here is the abstract from the paper (sorry, the pictures from Roma are completely unrelated, but I could not resist!):
We consider the problem of predictive density estimation for normal models under Kullback-Leibler loss (KL loss) when the parameter space is constrained to a convex set. More particularly, we assume that
is observed and that we wish to estimate the density of
under KL loss when μ is restricted to the convex set C⊂ℝp. We show that the best unrestricted invariant predictive density estimator p̂U is dominated by the Bayes estimator p̂πC associated to the uniform prior πC on C. We also study so called plug-in estimators, giving conditions under which domination of one estimator of the mean vector μ over another under the usual quadratic loss, translates into a domination result for certain corresponding plug-in density estimators under KL loss. Risk comparisons and domination results are also made for comparisons of plug-in estimators and Bayes predictive density estimators. Additionally, minimaxity and domination results are given for the cases where: (i) C is a cone, and (ii) C is a ball.