 Just received the good news that our paper Faster Hamiltonian Monte Carlo by Learning Leapfrog Scale by Wu Changye (吴昌烨), Pierre Pudlo, Julien Stoehr and myself, got accepted in Statistics & Computing! This is great in its own, but further concludes a story that started with Changye’s PhD thesis at Paris Dauphine in 2018, with a revision request from Statistics & Computing that stalled with Changye’s departing for industry in Shanghai and eventually resumed thanks to Julien’s massive investment in coding and improving the learning mechanism. It may also conclude my story with Statistics & Computing, where I am supposed to be the historically most prolific author (?), given the move by Springer to a cash-flow model on 01 January, 2027…
Archive for conformal Hamiltonian dynamics
faster HMC by learning
Posted in Books, Kids, Statistics, University life with tags algorithm, conformal Hamiltonian dynamics, eHMC, Hamiltonian Monte Carlo, HMC, leapfrog integrator, mirror descent, No-U-Turn sampler, NUTS, PhD thesis, population Monte Carlo, publication fees, revision, Scholarly Open Access, Shanghai, Springer Nature, Statistics & Computing, tempering, Università Ca' Foscari Venezia on September 23, 2026 by xi'aninvertible flow non equilibrium sampling (InFiNE)
Posted in Books, Statistics, University life with tags auxiliary variable, conformal Hamiltonian dynamics, energy, Gibbs sampler, Hamiltonian Monte Carlo, HMC, MCMC, multiple importance sampling, multiple mixtures, nested sampling, ODE, particle MCMC, unbiasedness, variational autoencoders on May 21, 2021 by xi'an With Achille Thin and a few other coauthors [and friends], we just arXived a paper on a new form of importance sampling, motivated by a recent paper of Rotskoff and Vanden-Eijnden (2019) on non-equilibrium importance sampling. The central ideas of this earlier paper are the introduction of conformal Hamiltonian dynamics, where a dissipative term is added to the ODE found in HMC, namely
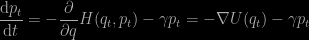
which means that all orbits converge to fixed points that satisfy ∇U(q) = 0 as the energy eventually vanishes. And the property that, were T be a conformal Hamiltonian integrator associated with H, i.e. perserving the invariant measure, averaging over orbits of T would improve the precision of Monte Carlo unbiased estimators, while remaining unbiased. The fact that Rotskoff and Vanden-Eijnden (2019) considered only continuous time makes their proposal hard to implement without adding approximation error, while our approach is directly set in discrete-time and preserves unbiasedness. And since measure preserving transforms are too difficult to come by, a change of variable correction, as in normalising flows, allows for an arbitrary choice of T, while keeping the estimator unbiased. The use of conformal maps makes for a natural choice of T in this context.
 The resulting InFiNE algorithm is an MCMC particular algorithm which can be represented as a partially collapsed Gibbs sampler when using the right auxiliary variables. As in Andrieu, Doucet and Hollenstein (2010) and their ISIR algorithm. The algorithm can be used for estimating normalising constants, comparing favourably with AIS, sampling from complex targets, and optimising variational autoencoders and their ELBO.
I really appreciated working on this project, with links to earlier notions like multiple importance sampling à la Owen and Zhou (2000), nested sampling, non-homogeneous normalising flows, measure estimation à la Kong et al. (2002), on which I worked in a more or less distant past.


