Archive for Hamiltonian

non-reversible MCMC [comments]

Posted in Books, Mountains, pictures, Statistics, University life with tags , , , , , on May 26, 2015 by xi'an

[Here are comments made by Matt Graham that I thought would be more readable in a post format. The beautiful picture of the Alps above is his as well. I do not truly understand what Matt’s point is, as I did not cover continuous time processes in my discussion…]

In terms of interpretation of the diffusion with non-reversible drift component, I think this can be generalised from the Gaussian invariant density case by

dx = [ – (∂E/∂x) dt + √2 dw ] + S’ (∂E/∂x) dt

where ∂E/∂x is the usual gradient of the negative log (unnormalised) density / energy and S=-S’ is a skew symmetric matrix. In this form it seems the dynamic can be interpreted as the composition of an energy and volume conserving (non-canonical) Hamiltonian dynamic

dx/dt = S’ ∂E/∂x

and a (non-preconditioned) Langevin diffusion

dx = – (∂E/∂x) dt + √2 dw

As an alternative to discretising the combined dynamic, it might be interesting to compare to sequential alternation between ‘Hamiltonian’ steps either using a simple Euler discretisation

x’ = x + h S’ ∂E/∂x

or a symplectic method like implicit midpoint to maintain reversibility / volume preservation and then a standard MALA step

x’ = x – h (∂E/∂x) + √2 h w, w ~ N(0, I)

plus MH accept. If only one final MH accept step is done this overall dynamic will be reversible, however if a an intermediary MH accept was done after each Hamiltonian step (flipping the sign / transposing S on a rejection to maintain reversibility), the composed dynamic would in general be non-longer reversible and it would be interesting to compare performance in this case to that using a non-reversible MH acceptance on the combined dynamic (this alternative sidestepping the issues with finding an appropriate scale ε to maintain the non-negativity condition on the sum of the vorticity density and joint density on a proposed and current state).

With regards to your point on the positivity of g(x,y)+π(y)q(y,x), I’m not sure if I have fully understood your notation correctly or not, but I think you may have misread the definition of g(x,y) for the discretised Ornstein-Uhlenbeck case (apologies if instead the misinterpretation is mine!). The vorticity density is defined as the skew symmetric component of the density f of F(dx, dy) = µ(dx) Q(x, dy) with respect to the Lebesgue measure, where µ(dx) is the true invariant distribution of the Euler-Maruyama discretised diffusion based proposal density Q(x, dy) rather than g(x, y) being defined in terms of the skew-symmetric component of π(dx) Q(x, dy) which in general would lead to a vorticity density which does not meet the zero integral requirement as the target density π is not invariant in general with respect to Q.

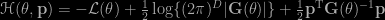
Pre-ordinary meeting

Posted in R, Statistics, Travel, University life with tags , , , , , on October 8, 2010 by xi'an

Those are the slides for the (basic) introduction of the paper by Mark Girolami and Ben Calderhead at the RSS next week. Not to be confused with my comments on the paper.

Riemann, Langevin & Hamilton

Posted in Statistics, University life with tags , , , , , on September 27, 2010 by xi'an

In preparation for the Read Paper session next month at the RSS, our research group at CREST has collectively read the Girolami and Calderhead paper on Riemann manifold Langevin and Hamiltonian Monte Carlo methods and I hope we will again produce a joint arXiv preprint out of our comments. (The above picture is reproduced from Radford Neal’s talk at JSM 1999 in Baltimore, talk that I remember attending…) Although this only represents my preliminary/early impression on the paper, I have trouble with the Physics connection. Because it involves continuous time events that are not transcribed directly into the simulation process.

Overall, trying to take advantage of second order properties of the target—just like the Langevin improvement takes advantage of the first order—is a natural idea which, when implementable, can obviously speed up convergence. This is the Langevin part, which may use a fixed metric M or a local metric defining a Riemann manifold, G(θ). So far, so good, assuming the derivation of an observed or expected information G(θ) is feasible up to some approximation level. The Hamiltonian part that confuses me introduces a dynamic on level sets of

\mathscr{H}(\theta,\mathbf{p})=-\mathcal{L}(\theta)+\frac{1}{2}\log\{(2\pi)^D|\mathbf{G}(\theta)|\}+\frac{1}{2}\mathbf{p}^\text{T}\mathbf{G}(\theta)^{-1}\mathbf{p}

where p is an auxiliary vector of dimension D. Namely,

\dot{\mathbf{p}} = \dfrac{\partial \mathscr{H}}{\partial \mathbf{p}}(\theta,\mathbf{p})\,,\qquad\dot{\theta}=\dfrac{\partial \mathscr{H}}{\partial \theta}(\theta,\mathbf{p})\,.

While I understand the purpose of the auxiliary vector, namely to speed up the exploration of the posterior surface by taking advantage of the additional energy provided by p, I fail to understand why the fact that the discretised (Euler) approximation to Hamilton’s equations is not available in closed form is such an issue…. The fact that the (deterministic?) leapfrog integrator is not exact should not matter since this can be corrected by a Metropolis-Hastings step.

While the logistic example is mostly a toy problem (where importance sampling works extremely well, as shown in our survey with Jean-Michel Marin), the stochastic volatility is more challenging and the fact that the Hamiltonian scheme applies to the missing data (volatility) as well as to the three parameters of the model is quite interesting. I however wonder at the appeal of this involved scheme when considering that the full conditional of the volatility can be simulated exactly…