 At JSM, John Kimmel gave me a copy of the Handbook of Markov chain Monte Carlo, as I had not (yet?!) received it. This handbook is edited by Steve Brooks, Andrew Gelman, Galin Jones, and Xiao-Li Meng, all first-class jedis of the MCMC galaxy. I had not had a chance to get a look at the book until now as Jean-Michel Marin took it home for me from Miami, but, as he remarked in giving it back to me last week, the outcome truly is excellent! Of course, authors and editors being friends of mine, the reader may worry about the objectivity of this assessment; however the quality of the contents is clearly there and the book appears as a worthy successor to the tremendous Markov chain Monte Carlo in Practice by Wally Gilks, Sylvia Richardson and David Spiegelhalter. (I can attest to the involvement of the editors from the many rounds of reviews we exchanged about our MCMC history chapter!) The style of the chapters is rather homogeneous and there are a few R codes here and there. So, while I will still stick to our Monte Carlo Statistical Methods book for teaching MCMC to my graduate students next month, I think the book can well be used at a teaching level as well as a reference on the state-of-the-art MCMC technology. Continue reading
Archive for perfect sampling
Handbook of Markov chain Monte Carlo
Posted in Books, R, Statistics, University life with tags ABC, adaptive MCMC methods, base-jumping, Biometrika, book review, edited book, Gaussian state spaces, history of statistics, Markov chains, MCMC, Monte Carlo Statistical Methods, perfect sampling, R, reversible jump, simulation on September 22, 2011 by xi'anAnother Bernoulli factory
Posted in R, Statistics with tags Bernoulli, MCMC, perfect sampling on February 14, 2011 by xi'an The paper “Exact sampling for intractable probability distributions via a Bernoulli factory” by James Flegal and Radu Herbei got posted on arXiv without me noticing, presumably because it came out just between Larry Brown’s conference in Philadelphia and my skiing vacations! I became aware of it only yesterday and find it quite interesting in that it links the Bernoulli factory method I discussed a while ago and my ultimate perfect sampling paper with Jim Hobert. In this 2004 paper in Annals of Applied Probability, we got a representation of the stationary distribution of a Markov chain as

where
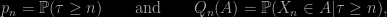
the stopping time τ being the first occurrence of a renewal event in the split chain. While 
Monte Carlo Statistical Methods third edition
Posted in Books, R, Statistics, University life with tags Bayesian lasso, hierarchical Bayesian modelling, Introducing Monte Carlo Methods with R, Markov chains, MCMC, mixture estimation, Monte Carlo Statistical Methods, nested sampling, perfect sampling, Peskun ordering, R, Rao-Blackwellisation, regeneration, slice sampling on September 23, 2010 by xi'an Last week, George Casella and I worked around the clock on starting the third edition of Monte Carlo Statistical Methods by detailing the changes to make and designing the new table of contents. The new edition will not see a revolution in the presentation of the material but rather a more mature perspective on what matters most in statistical simulation:


