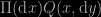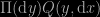In connection with questions I had posted earlier about the interesting paper of Raphael Gottardo and Adrian Raftery, I got several emails from Raphael that helped with my understanding of the paper, the main point being that having the target being defined against the same measure as the proposal does not prevent from having zero components in this target, thus incorporates within-Gibbs moves quite naturally. Arnaud Doucet also pointed out to me that using kernels with Dirac masses is possible when looking at them from an empirical measure point of view, as explained in this short note. As a coincidence, Raphael also added some comments and explanations on the first post.
Archive for reversible jump
MCMC with mutually singular distributions (2)
Posted in Statistics with tags Bayesian statistics, MCMC, reversible jump on March 31, 2009 by xi'anMCMC with mutually singular distributions
Posted in Statistics with tags Bayesian statistics, MCMC, reversible jump on March 19, 2009 by xi'anA paper that recently appeared in the latest issue of JCGS deals with this important issue of using mutually singular proposals, written by Raphael Gottardo and Adrian Raftery. I personally find the problem quite interesting because it covers major applications like Bayesian model choice and Bayesian nonparametric density estimation. The beginning of the paper recalls some basics about computing densities for measures that are mixtures wrt mutually exclusive measures. (This may sound obvious to many, but there is this important remark that, for measures involving Lebesgue and Dirac components at 

Now, I find it rather restrictive that in the paper both the target and the proposal are defined against the same dominating measure