 Li, Nott, Fan, and Sisson arXived last week a new paper on ABC methodology that I read on my way to Warwick this morning. The central idea in the paper is (i) to estimate marginal posterior densities for the components of the model parameter by non-parametric means; and (ii) to consider all pairs of components to deduce the correlation matrix R of the Gaussian (pdf) transform of the pairwise rank statistic. From those two low-dimensional estimates, the authors derive a joint Gaussian-copula distribution by using inverse pdf transforms and the correlation matrix R, to end up with a meta-Gaussian representation
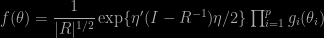
where the η’s are the Gaussian transforms of the inverse-cdf transforms of the θ’s,that is,
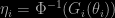
Or rather
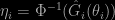
given that the g’s are estimated.
This is obviously an approximation of the joint in that, even in the most favourable case when the g’s are perfectly estimated, and thus the components perfectly Gaussian, the joint is not necessarily Gaussian… But it sounds quite interesting, provided the cost of running all those transforms is not overwhelming. For instance, if the g’s are kernel density estimators, they involve sums of possibly a large number of terms.
One thing that bothers me in the approach, albeit mostly at a conceptual level for I realise the practical appeal is the use of different summary statistics for approximating different uni- and bi-dimensional marginals. This makes for an incoherent joint distribution, again at a conceptual level as I do not see immediate practical consequences… Those local summaries also have to be identified, component by component, which adds another level of computational cost to the approach, even when using a semi-automatic approach as in Fernhead and Prangle (2012). Although the whole algorithm relies on a single reference table.
The examples in the paper are (i) the banana shaped “Gaussian” distribution of Haario et al. (1999) that we used in our PMC papers, with a twist; and (ii) a g-and-k quantile distribution. The twist in the banana (!) is that the banana distribution is the prior associated with the mean of a Gaussian observation. In that case, the meta-Gaussian representation seems to hold almost perfectly, even in p=50 dimensions. (If I remember correctly, the hard part in analysing the banana distribution was reaching the tails, which are extremely elongated in at least one direction.) For the g-and-k quantile distribution, the same holds, even for a regular ABC. What seems to be of further interest would be to exhibit examples where the meta-Gaussian is clearly an approximation. If such cases exist.
 After watching Donald Trump apparently shooting himself in the foot with his statement about prosecuting women seeking illegal abortions, it is even more ghastly to hear Ted Cruz’s subsequent declaration:


